Foreclosure Support › Questions
Why does the mortgage payout keep growing?
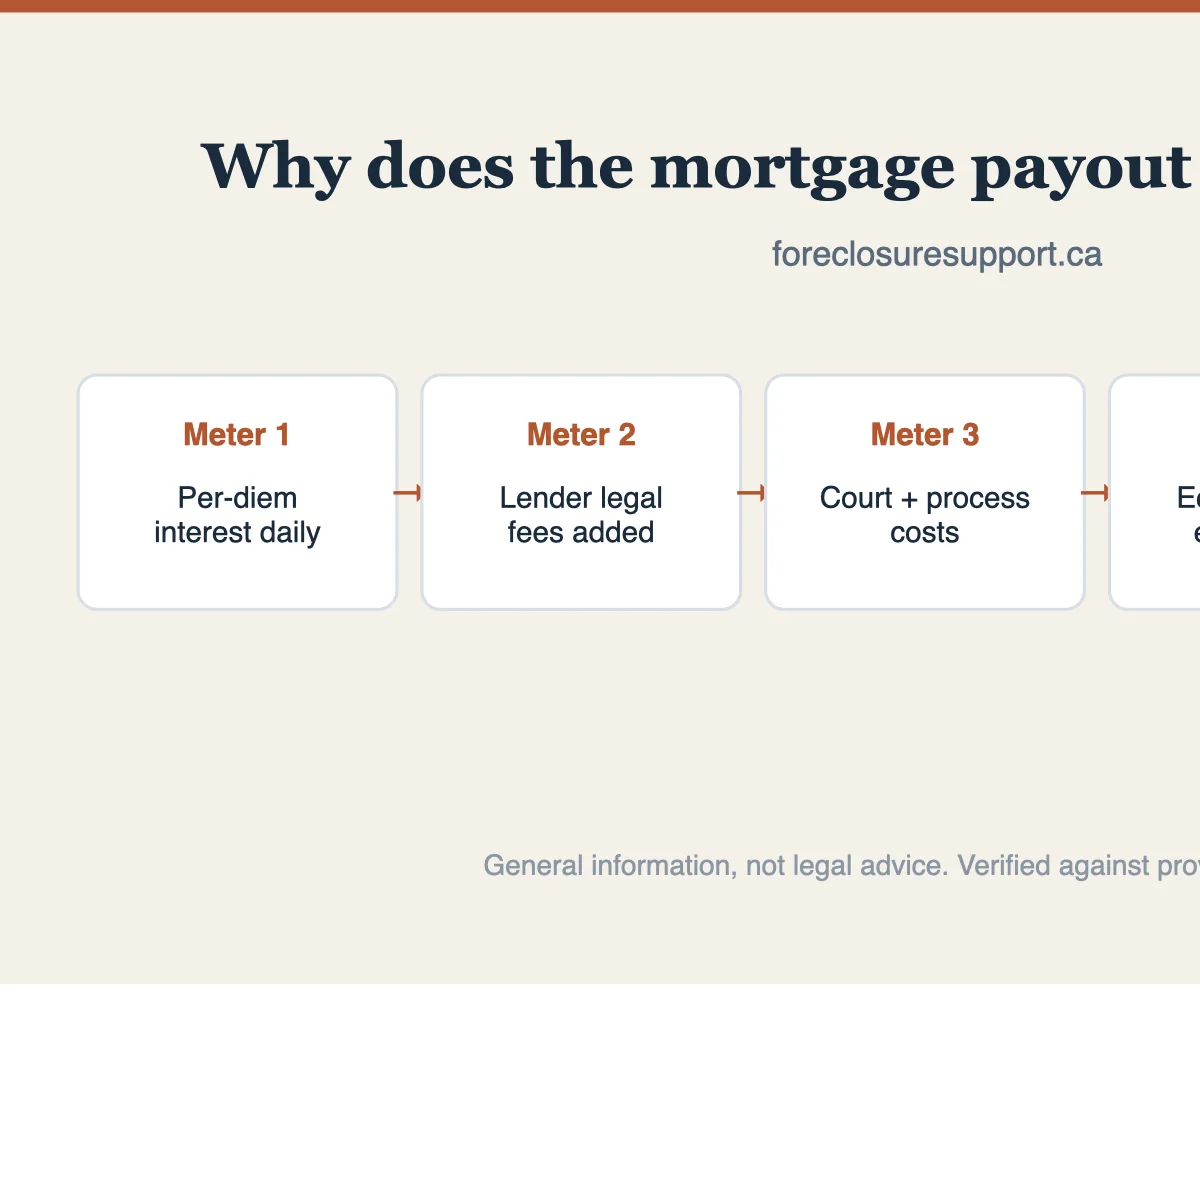
The three meters, explained
When homeowners compare payout statements and find thousands of dollars of growth in a few weeks, it usually breaks down like this:
- Per-diem interest. Your mortgage keeps charging interest daily on the whole outstanding balance — arrears included. On a $300,000 balance at today's rates, that alone can run $40-60 every day, seven days a week.
- The lender's legal fees — billed to you. Most mortgages let the lender add enforcement costs to the debt. Their lawyer's letters, filings, and court appearances all land on your payout, at law-firm rates.
- Process costs. Court filing fees, process servers, title searches, appraisals ordered by the lender — each one added to the total secured against your home.
None of this is hidden or improper — it's how mortgage enforcement works across Canada. But it means time itself is the expense: the same house, sold three months earlier, leaves meaningfully more in your pocket.
How to read a payout statement
Ask your lender (or their lawyer) for a written payout statement and check four lines: the principal balance, the arrears and accrued interest, the per-diem rate (what each additional day costs you), and the fees and costs added. In Ontario you can formally demand a statement of the amounts owing, and enforcement can pause if the lender doesn't answer within 15 days — a genuinely useful lever. In every province, you're entitled to know what you owe; if a number looks inflated, your lawyer can challenge unreasonable charges.
Stopping the meter
Only two things stop the growth: reinstating (where available — paying the arrears and costs to restore the mortgage) or paying the mortgage out — by refinancing or by selling. A private sale on your own timeline typically closes faster than a court-supervised one and at a better price, which attacks the problem from both ends: the meter stops sooner, and there's more left when it does. Run your numbers in the calculator, and see how a cash sale actually works if speed matters. If there's equity in the home, protecting it is mostly a race against the per-diem — and it's a race you can still win in almost every province if you start now.
Quick answers
Can the lender really charge me their legal fees?
Usually yes — most Canadian mortgages allow reasonable enforcement costs to be added to the debt. Your own lawyer can review whether specific charges are reasonable and challenge ones that aren't.
How do I find out exactly what I owe today?
Request a written payout statement from your lender or their lawyer. It should show the balance, arrears, per-diem interest rate, and added costs — and it goes stale quickly, so date it.
Does the growth stop once the court process starts?
No — the opposite. Legal activity is when fees accumulate fastest, and interest never pauses. The process starting is a reason to act faster, not to wait.
Talk it through with a person
Every situation above has a version where you keep the house and a version where you sell well — a free 15-minute call maps yours. No fees, no pressure, and if the right answer doesn't involve us, we'll say so.
See what you'd walk away with — three scenarios → Alberta foreclosure guide → Ontario power of sale, explained →
Keep reading
- How selling to a cash buyer actually works
- Will you owe money after foreclosure?
- Missed a payment in Alberta? The real timeline
Sources
- Financial Consumer Agency of Canada — mortgages and default
- Mortgages Act, RSO 1990, c M.40, s. 22 (arrears statement demand)